Plays here from YouTube when you press play. Open on YouTube
Published . Prices, rates and counts in this video were current on that date. This month's numbers are on Market Data. Terence Richardson joined Compass in September 2025, after this video was published.
What is this video about?
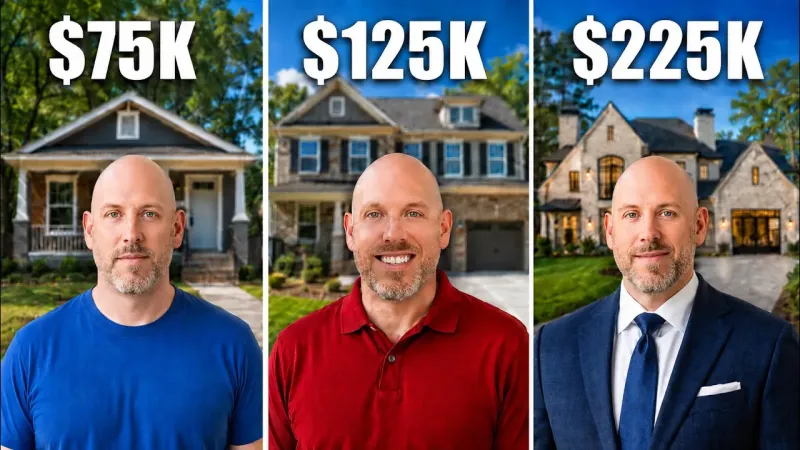
“How Much House You Can ACTUALLY Afford in Atlanta (By Salary)” is a 15-minute video by Terence Richardson, a Realtor with Compass in Metro Atlanta. It was published on June 21, 2025 on his YouTube channel, Terence Richardson - Atlanta Real Estate.
In this video, I show you how much house 3 different salary levels can actually afford right now in Atlanta. Stick with me and I'll show you the formula you should use to figure out what you can afford too.
Transcript
This comes from YouTube’s automatic captions, set into paragraphs. Place names the captions misspelled were corrected. 4 figures or words the captions misheard were corrected after checking them against the video’s script or a second transcription. Nothing else was added or reworded. Captions can still mishear a word or a number, so check a figure against the video before you rely on it. Captions read November 16, 2026.
The affordability trap 0:00
You've seen the houses people bought back in 2022, yet the pre-approval letter you just received has such a low number. That's it. It feels unfair. It feels like you've been robbed of your buying power because of today's rockhigh interest rates. But here's the crazy part. Even that number is still a trap and one that could lead to a huge financial mistake if you're not careful. I'm going to break down three common salaries right here in Atlanta and show you what you can currently buy in today's market.
And at the end, I'm going to give you a formula that allows you to take back control so you won't be house poor.
Scenario 1: $75k income 0:33
First up, let's take a look at a $75,000 annual salary. That's pretty common for a young professional here in Atlanta. And if that's you, that works out to be about $4,750 every single month of net take-home pay. So, you're ready to stop renting. You want to buy your first home, start building equity. Chances are you're going to be looking at an FHA loan to do that. So, you've been playing around with these calculators.
You've been putting numbers in to see what you could potentially qualify for. And even based on what was possible just a couple years ago, you're probably hoping for something in the low 300,000s or even higher. But your lender gets back to you with that pre-approval letter and it says, "Congratulations, you're pre-approved for a house up to 268,000." And you think, "$ 268,000? Well, that's disappointing. That's not going to get me into the neighborhoods that I was interested in."
Now, let's take a look at that payment on that $268,000 house, and we're going to go to an affordability calculator that I have right here. So, we're going to go ahead and we're going to put in that your annual income is $75,000. You're single in this scenario. So, we're going to keep your tax filing status as single. You may or may not have debts, but for the purpose of this calculation, we're going to say that you don't have any.
If you have a car, you've paid it off. You don't have you're not carrying any credit card balances. You've paid those off as well. You don't even have student loan debt. Congratulations. Not factoring any of that right now. If you did have that and you were using this calculator, you'd want to put it in where you see monthly debts. We're going to assume that you're going to buy something within the city limits of Atlanta.
And this basically just breaks down what the property taxes would be in the different cities if you're within city limits. Now, the loan type, we're going to switch from conventional. We're looking at FHA. It's a lower down payment. It's 3.5% as you can see and the average rate for an FHA loan today is 6.5%. So that's what we're going to go with and it's advertised over a 30-year period which means you've got 30 years to pay back the loan.
So let's take a look at what we get. So the lender in our scenario approved you based on a 35% debt to income ratio. That's the US average for FHA loans and it's basically they look at your annual income. They say no more than 35% of that can be used towards qualifying for a mortgage payment. And it's 35% of the annual divided by 12 to figure out what it is on a monthly basis.
So that's how they get you to 268,000 using a 35% gross income. Uh it's basically your debt to income ratio. Now the payment breaks down as 1664 is your principal and interest. Then you've got your property taxes of 311 every single month. You've got homeowners insurance at 101 and your mortgage insurance premium is $121 every single month. That brings you approximately to $2,200 a month to be able to afford a house up to $268,000.
So you take your take-home of $4750 and you've got a payment of roughly 2,200. Well, that's roughly 46% of your overall take-home pay. That doesn't even include all of your utilities and internet and you know you've got a lot of month left over after you've got potentially a car payment. You've got food you got to pay for entertainment. Lots of different things closed, right? So, how does spending almost 50% of your take-home pay on a house feel when you're getting your first house?
Well, probably doesn't feel very good, but that's what the lender says you're technically qualified for on paper. As a matter of fact, they can even push this all the way up to a 50% ratio if you have the right credit, if you have stable income, if you have enough reserves, aka cash, sitting in your bank account. Check this out. You could theoretically get approved for a house all the way up to $382,000.
Wouldn't that be cool? Well, it would until you find out what the payment would be. The payment on this thing would be 3130 every single month. So, this number here is suffocating. The US average of 35%, the 268 is still tight. Both of these numbers are traps, and that's what you're going to find on your pre-approval letter. So, what's the smart number? Now, you're not going to like the house price. Now, the play here isn't to get depressed over this number.
I know what you're thinking. I know what you're thinking. 194,000. You can't buy anything in Atlanta for 194,000. Well, I'm going to show you a couple of possibilities here in just a moment, but the idea is not to get depressed, but to get strategic because, not sure if you realize this, but you're not going to live in the first house that you buy for 30 years. You're not going to see that mortgage paid off while you live there.
You might see it paid off if you eventually turn it into a rental property, which is super smart when you buy your next one. All you got to do to buy your next one while keeping your first one is to save up the down payments, but that's for a different video. No, it's time to get tactical about this. So, let me show you what you can buy in Atlanta today for up to 194,000.
Now, the first house I'm going to show you is inside the perimeter because chances are if you're a young professional, then you're going to be working ITP, right? So, this is indicator. It's a three-bedroom, one bath, approximately 1,300 ft², and it's been completely renovated all for 190,000. It's a nice little starter home, and that's exactly what it is. Now, if single family is not your thing and you would rather look at a town home, we can do that as well.
You got to know about this. So, when you get your pre-approval letter and it says that you're qualified for whatever number, right? 200,000 300,000. That's all in. Don't go looking at condos and town homes that are right at 300 because the lender will factor in the HOA fee. And so, you have to kind of work backward because the lender is not approving you for the purchase price. The lender is approving you for the overall payment.
Think about it that way. And this makes a lot more sense. You've got this one over here for 175,000 in Lithonia. It's a two-bedroom, 1 and a half bath. It's nice on the inside. It's been renovated as well. It's got new floors, new paints, and if condos are more your thing. Well, we've got this one that's over here in Smyrna. Now, Smyrna is a great location, right? This is a one-bedroom, one bath, under 1,000 ft².
So, it's definitely on the smaller side. It's 159,000. Call it 160,000. But as you can see, these are three moveinready properties. So when you a lot of people their first reaction will be there are no homes left in Atlanta under 200,000. Those homes that are left are major fixer uppers or they're in the worst parts of town that are riddled with crime. Not necessarily. So do your homework. You can see that there are still some possibilities out there.
Scenario 2: $125k income 7:10
Next, let's take a look at a household earning $125,000 per year. This couple is bringing in every single month about $8,200 after taxes. We'll call it $8167. And this could be a married couple with very young kids. Like could be a teacher, project manager, something like that. And they need more space. They need room for the kids. Schools are starting to matter more as well. And they have enough saved up to be able to put 10% down.
So, we're going to be looking at a 10% down conventional loan. So, we'll calculate it. And your pre-approval letter, congratulations. It shows that you're qualified for $579,000. So, let's dive into what that looks like. Now, that $4,486 payment is huge when you consider that you're taking home 81, call it $8,200 every single month after taxes. This is $55% of your take-home pay. Is that comfortable? I don't think so. I don't think that's comfortable for anybody.
there's not enough month left to cover everything else and still be able to live comfortably. Now, this is the bank's number. This is one of the traps and this is why I always say you've got to do what's in your best interest and the lender is going to try and get you to do what's in their best interest. So, these calculators are very helpful, specifically this one, because I've built into it what the safe number is.
So, if you take a look at what I recommend, which is the 33% of net, then you're going to look at a house that's $352,000. It's over $200,000 less. Now, what does that do to the payment? Well, instead of having a payment that's $4,500 a month, you now have a payment that's closer to $2,700 a month. Think of it this way. That $1,755 that you're saving every single month by buying a $352,000 house instead of a $579,000 house works out to be over $21,000 a year.
What would you do with an extra $21,000? I mean, you could accelerate your retirement investing. You can fully fund children, college accounts, Roth IAS, all that stuff. You have a lot of opportunity for wealth building, right? Cuz you're not house poor. So, if you're in the market for a single family home, you've got this house over here in Fairburn. This is a 4-bedroom, 2 and a half bath for 350,000. It's 2300 ft².
Really nice on the interior. If town homes are more your thing, then for 300,000. And again, we're looking at a lower purchase price because of the HOA fees. If you considered living in Stone Crest, you can get this one for 300. It's a three-bedroom, 2 and a half bath. It's roughly 2100 ft², which is a really good size for a town home, and it's got a two-car garage. And if condos are more your thing, then for 300,000 in Kennesaw, Cobb County is very popular, you can get this one here over in Rydenower.
It's a three-bedroom, 2 and a half bath, almost $1,800 ft².
Scenario 3: $225k income 10:08
Now, let's take a look at a $225,000 level of income. So, it's obviously a more established household. It's a family. They've got kids that are getting a little bit older and now they're starting to consider what house to buy to be their forever home. And at this level of income, their take-home pay after taxes, it's approximately $14,000 every single month. And they're going to be looking not at a 10% down conventional, but they've got enough saved up now for a 20% down conventional.
Either they had it saved up or that middle house that they sold, they took the equity of that and they're putting it into the next house. So, what do you think that number is? What do you think the lender would approve this borrower for? So, at 225,000, if they went all the way up to 45, we'll call it 43 for the purpose of this calculator here. It's a million-doll house. It's $1.2 million to be exact.
Not bad, right? What kind of a payment does that come with? Almost $8,100 every single month. 8,100 out of 14,000 take home. Like 14,000 seems like a really big number, but when you're taking 8,000 and you're left with less than six, that's over 60% of your take-home. And that doesn't even include utilities, HOA fees, the cost of maintaining a house, because if you have a house like this, chances are you're paying somebody else to do the landscaping.
Like, there's a lot of extra expenses that go into a more expensive house. So you'd find yourself on the real wrong side of affordability if you were to buy a house at this level. My take, right? So what's more reasonable than that? Well, often times banks will also use a 28% of gross. At 28% of gross, you're looking at something closer to 780,000. Now at 781,000, your mortgage payment is roughly 5256 every single month.
And that's definitely a lot better than $8,000 plus. But is it the right move? Now, wealthy people don't ask if they can make a payment. Wealthy people ask, "What's the smartest thing I can do with my money?" So, what's the smart number? And you know where I'm going with this. 33% of take-home. 33% of take-home will drop the price of the house by almost 100,000. So, you go from 781 down to 683, but you can still get a lot of really nice houses for $683,000.
Now, that payment's 45 almost $4,600. So, you're saving about $662 there. Now, at this point, you're making your money work for you, not just for your house. So, what exactly can you get for $684,000? Well, the answer to that is a lot. And if I'm going to look at single family homes for these next three examples, because I think that if you're at this stage of your career, chances are you want a single family house.
Does that mean that there aren't exceptions and people still want town homes and and condos? Absolutely. But it's my video. I'm going to show you three single families. So, if you want to live in Alpharetta, you've got this one here for 675,000, 4-bedroom, 2 and a half bath, just a hair over 3,000 square ft. Nice family home. And then you've got this one over here in Suwanee. Suwanee also has been redhot over the last couple of years.
This is 675. It's a five-bedroom, 4 and a half bath. Check out that square footage. It's 4200 ft². And this one has a finished basement. And then you've got this one over here in Marietta. So, this is West Cobb. It's Hill Grove High School, which is very popular. It's a five-bedroom, five bath on over 4500 ft², and it's got an unfinished basement. So, it goes to show you how big this house is, because at 4500, it's not counting finished space in the basement.
So, I've said it before, but if you want to see the inside pictures of any of these houses, just check the description.
The 33% rule formula 13:52
All of the links are there. So, what exactly is a 33% net rule? Well, it's very simple. Basically, you take your actual monthly take-home pay. That's after your employer's removed your taxes, your contributions to 401, anything that comes out of your pay. It's basically the amount that hits your account and you want to know what your monthly amount is. So, you take your monthly amount and you divide it by three. Super easy.
That number is what your housing payment is. And your housing payment is your mortgage, which is your principal, interest, property taxes, and property insurance. If you keep that number at under a third of what your take-home pay is, you have a lot left over to cover everything else you're going to need to support that house and to support the life that you want to live. In other words, you won't be house poor.
Now, if you'd like to play around with the calculator that I use in today's video, all you got to do is go to my website. I created them and I've got not one, not two, but three different calculators for you to use. Starting with this own versus rent calculator. And if it makes more sense for you to rent, it's going to tell you. I'm not holding anything back. Then you've got the how much house can I afford calculator and I've got a great mortgage calculator.
Now, I built this tool for Atlanta specifically. So, when you choose a city, it's going to pull the tax rate for property taxes for that specific city, giving you a more accurate number. No other calculator out there does that.

About Terence Richardson
Terence Richardson is a Realtor with Compass and the founder of the Terence Richardson Group, which serves Metro Atlanta. He publishes Atlanta’s Housing Market Update every month on YouTube and in The Richardson Report.
